Retirement planning for educators

Your pension matters. So does everything around it.

About 85% of the families FortiGuard serves are educators. We help turn pension information and scattered retirement accounts into one understandable retirement picture.

The educator retirement picture

Four decisions. One coordinated plan.

Pension choices should not be made in isolation from workplace accounts, Social Security, family needs and the income you want later.

  1. 01

    Your pension system

    Put official pension estimates, benefit elections, service history and retirement timing into the context of your complete household plan.

  2. 02

    403(b) and 457(b) accounts

    Review supplemental accounts, fees, access rules, investment choices and the job each account needs to do before or during retirement.

  3. 03

    Job changes and rollovers

    Compare leaving an account in the plan, moving it, consolidating it or using part of it for retirement income—with the tradeoffs clearly documented.

  4. 04

    Income beyond the pension

    Coordinate pension income with Social Security, retirement accounts, savings, survivor needs and the years in which income may change.

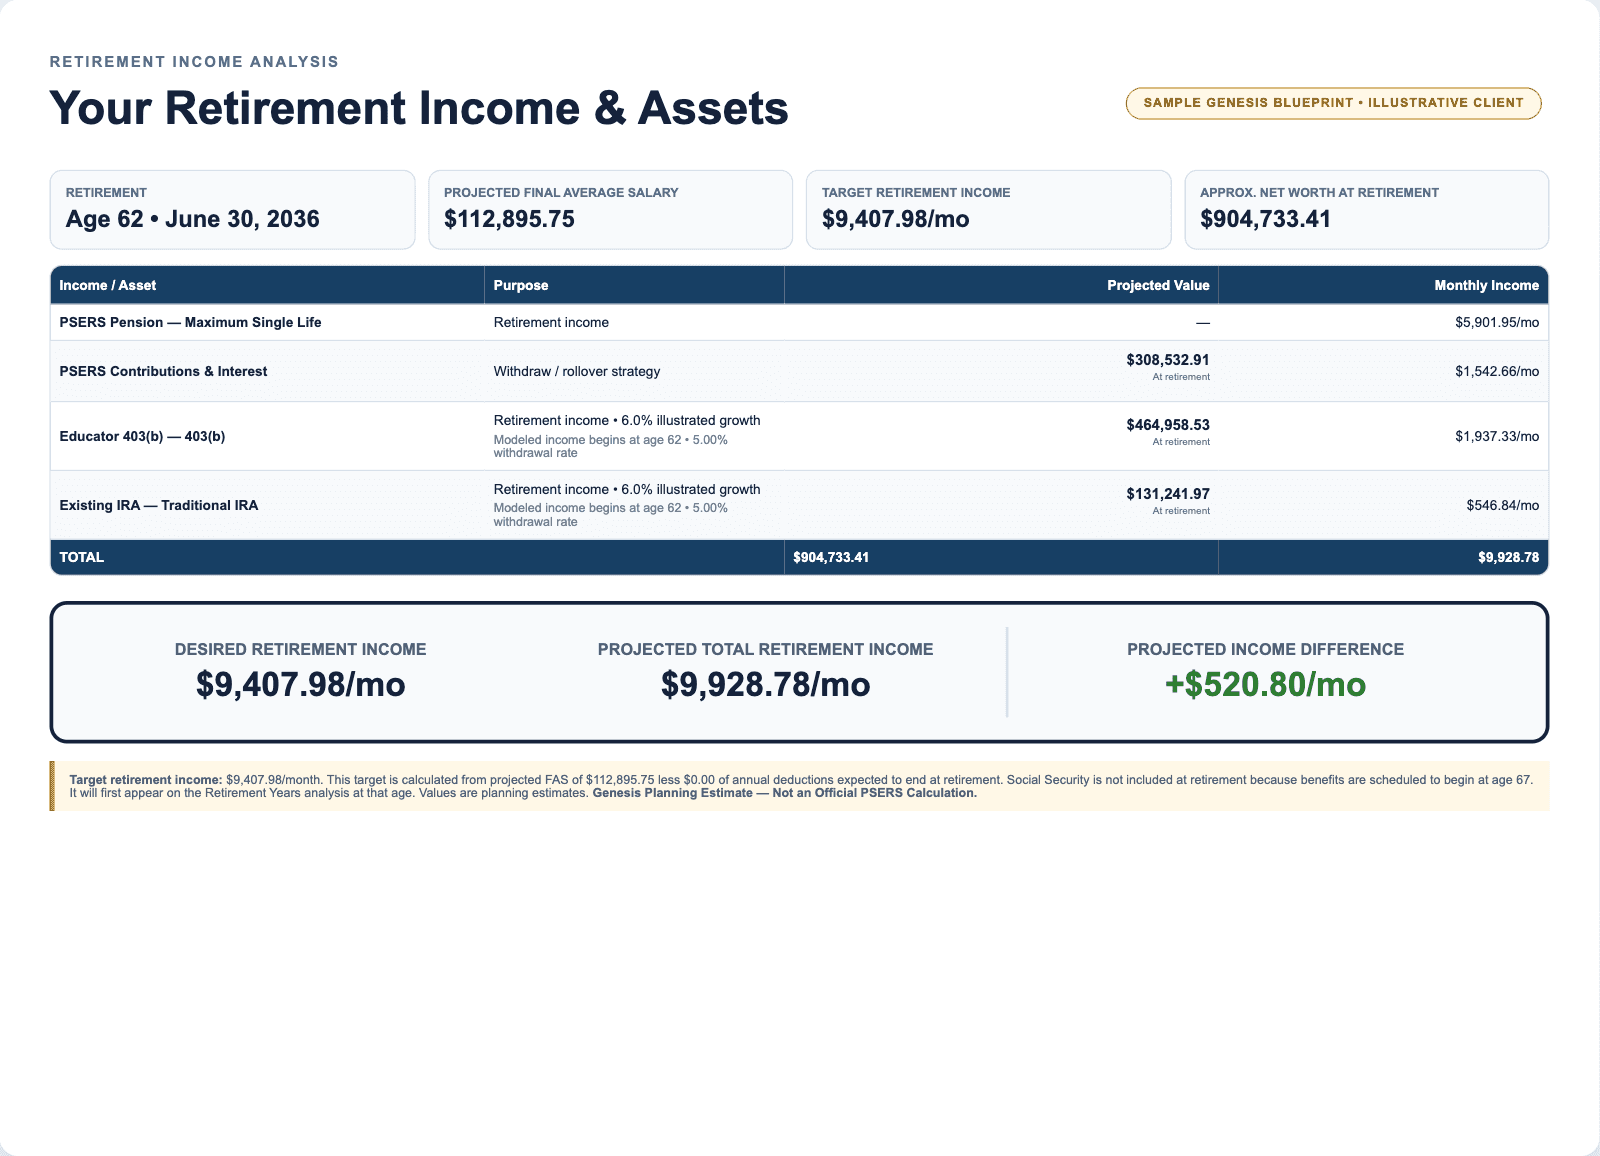
Example Genesis Retirement Blueprint retirement income analysis

Your complimentary Genesis Blueprint

See the pension, accounts and income together.

After your consultation, a personalized visual report can help you understand how today’s decisions affect the retirement years ahead.

  • ✓Retirement-income sources and timing
  • ✓Pension and Social Security coordination
  • ✓Account values and potential income roles
  • ✓Planning strengths, gaps and next questions

Fictional client example for illustration only. The report is educational and is not an official pension calculation, recommendation or guarantee.

Common questions

Start with what you need to understand.

Can an educator roll over a 403(b) after leaving a school employer?

A former-employer 403(b) is commonly eligible for distribution, but the plan administrator must confirm the available options and paperwork. Eligibility alone does not determine whether a rollover is the best choice.

How should a pension and supplemental accounts work together?

The pension may provide a foundation, while 403(b), 457(b), IRA and other assets can support flexibility, changing income needs, emergencies and legacy goals. The right roles depend on the household and plan rules.

Do you only work with Pennsylvania educators?

No. FortiGuard works with educators and other professionals across a broad range of licensed states. Our team has specialized experience with Pennsylvania PSERS, while the planning process applies to many pension and workplace retirement systems.

What will I receive after a consultation?

You receive a complimentary Genesis Retirement Blueprint that organizes the information discussed into a visual report showing income sources, timing, strengths and planning considerations.

Clarity before movement

Before you move a 403(b), 457(b), TSP or other account, see how it fits.

Start your complimentary review

FortiGuard Financial is not affiliated with or endorsed by PSERS or any government agency. Official pension estimates, eligibility and plan rules must be confirmed by the applicable retirement system or plan administrator.

Start Your Educator Review